IVF Cost in 2026: A Realistic Breakdown for Intended Parents
IVF Cost in 2026: A Realistic Breakdown for Intended Parents
For most families, the first hard question about IVF is simply how much it costs, and the honest answer is that the headline number hides as much as it reveals. A single IVF cycle in the United States typically runs from the low five figures to around thirty thousand dollars depending on location, clinic, and add-ons, and that figure usually excludes the medications, genetic testing, and storage that many patients need. This guide breaks down where the money goes, what moves the total, and how IVF cost fits into a broader surrogacy budget.
The component breakdown
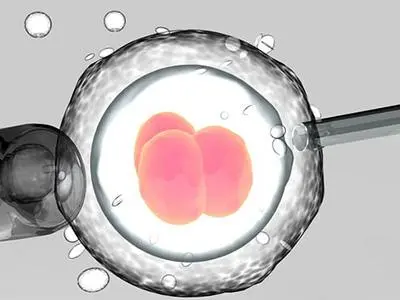
A standard IVF cycle includes several billable parts: the initial consultation and testing, ovarian stimulation medications, monitoring ultrasounds and bloodwork, the egg retrieval procedure, fertilization in the lab, embryo culture, and the embryo transfer. Each is priced separately at most clinics, which is why a quoted “cycle price” can look very different from the final invoice. Understanding the line items is the only way to compare programs fairly, because two clinics quoting similar totals may bundle very different services.
What medications add
Stimulation medications are a major and often surprising cost, frequently several thousand dollars per cycle and more for higher doses or longer protocols. Because dosing depends on the patient’s response, the medication bill is one of the least predictable parts of the cycle. Patients should ask for an estimated medication range up front and confirm whether it is included in any quoted package, since leaving it out can understate the true cost by a wide margin.
Add-ons that change the total
Several optional but common services add to the bill. Preimplantation genetic testing identifies chromosomally normal embryos and is valued for improving per-transfer success, but it adds several thousand dollars. Intracytoplasmic sperm injection is often used when male factors are present. Embryo freezing and annual storage, and the later frozen embryo transfer, are additional line items. Each can be justified clinically, but together they can push a cycle well beyond the base price, so they belong in any realistic budget.
Why costs vary so widely
Geography is a large driver: clinics in major metropolitan areas tend to charge more than those in lower-cost regions. Clinic reputation and bundled programs also matter; some offer guaranteed or shared-risk packages that cost more up front but cap total exposure. The National Institutes of Health and fertility economists note that price transparency remains limited in this field, which is why intended parents must request itemized estimates rather than relying on advertised minimums.
Insurance and financing
Coverage for IVF varies dramatically by state and employer, with some mandates requiring certain plans to cover treatment and many others excluding it entirely. When coverage exists, it can reduce out-of-pocket cost substantially; when it does not, financing products, grants, and payment plans fill the gap for some families. Asking about both insurance and financing early, before committing to a clinic, often surfaces savings that change the affordable options.
IVF cost inside a surrogacy journey
For families using surrogacy, IVF is one component of a larger budget that also includes surrogate compensation, legal fees, and agency costs. The IVF portion covers egg retrieval, fertilization, testing, and the transfers into the surrogate, and getting it right the first time matters because every repeat cycle adds cost and time. Budgeting the IVF line item with its realistic add-ons, rather than a bare cycle price, prevents the common shock of discovering the true total only after treatment has begun.
Comparing clinics fairly
The only fair way to compare IVF prices is to line up identical itemized estimates, because a low headline number often omits medications, testing, or storage that another clinic includes. The National Institutes of Health and fertility economists have long noted that price opacity in this field makes comparison shopping hard, so patients must ask for the full bundle in writing. A clinic that itemizes willingly is easier to trust than one that quotes only a tempting minimum.
Medication cost management
Because stimulation drugs are a large and variable expense, asking about dose estimates, pharmacy options, and whether any medication is included can materially change the total. Some patients reduce cost by using a clinic’s preferred pharmacy or by discussing dose strategies with their physician, though safety always trumps savings. Building the medication line into the budget from the start, rather than discovering it mid-cycle, is one of the simplest ways to avoid financial surprise during an already stressful time.
Grants, loans, and payment plans
For families without insurance coverage, several financing routes exist: fertility-specific loans, clinic payment plans, and grants from nonprofit organizations that support family building. The reproductive medicine society points patients toward reputable financial resources, and applying early, before a cycle begins, often unlocks options that are unavailable mid-journey. Treating financing as part of planning, not a last resort, expands the set of clinics and protocols a family can realistically afford.
Total cost of a surrogacy-inclusive journey
When IVF sits inside a surrogacy journey, the IVF line is one of several, and the total often reaches well into six figures once surrogate compensation, agency, legal, and travel are included. The CDC’s ART resources help families understand the medical components, but the financial whole requires its own spreadsheet. The families who manage this best are those who budget the full arc, including likely repeat cycles, before the first transfer rather than reacting to each invoice as it arrives.
Hidden costs families forget
Beyond the obvious line items, several costs catch families off guard: travel and lodging for monitoring or retrieval, time off work, the cost of repeating a cycle that did not yield a pregnancy, and storage fees that accrue year after year if embryos remain frozen. None of these is large on its own, but together they can add thousands to the true total. Listing them explicitly in a budget, rather than hoping they will not apply, is the difference between a plan that holds and one that breaks under the first surprise.
Reducing cost without reducing care
There are legitimate ways to manage IVF cost without cutting corners on safety: using a clinic with transparent bundled pricing, asking whether a minimal-stimulation or natural-cycle approach fits your case, comparing pharmacy options, and timing financing applications before treatment begins. The aim is efficiency, not austerity, because the most expensive IVF cycle is the one that fails for the wrong reasons. A family that plans the full cost and seeks savings in the right places enters treatment with both clarity and confidence.
Planning for the multi-cycle reality
Because many families need more than one cycle to reach a live birth, the honest cost conversation includes the possibility of repeats, and budgeting for that reality up front prevents the worst financial stress. Setting aside a contingency, exploring financing before treatment, and choosing a clinic whose pricing is transparent all help a family absorb a second cycle without derailing the journey. The families who plan for the multi-cycle reality, rather than the best case, are the ones who actually reach the finish line with both a child and their finances intact.
Negotiating and asking the right questions
Few patients think to negotiate or probe IVF pricing, yet asking specific questions pays off: Is the quote all-in or base only? What happens if the cycle is canceled before retrieval? Are frozen embryo transfers priced separately? Clinics that answer plainly invite trust, and some will adjust package elements to fit your case. Approaching the cost conversation as an informed buyer, rather than a passive payer, often reveals savings and prevents the quiet add-ons that inflate a final bill beyond the number you agreed to.
Tracking spending as you go
Once treatment begins, keeping a running record of every charge, from the initial consult to storage renewals, turns an overwhelming total into a manageable series of line items you actually control. A simple spreadsheet with dates, amounts, and what each charge covered also makes it easier to spot billing errors, claim insurance reimbursement, and recognize when you have crossed into multi-cycle territory. Families who track spending actively tend to feel less at the mercy of the process and more like informed managers of a major investment, which is exactly the posture that protects both their finances and their peace of mind.
Frequently Asked Questions
What is the average IVF cost in 2026? A single cycle commonly ranges from about fifteen thousand to thirty thousand dollars before medications and add-ons, with total realistic cost often higher once testing and storage are included.
Does insurance cover IVF? It depends on your state and plan; some mandates require coverage and many exclude it, so verifying your specific benefits is essential before choosing a clinic.
Why is medication so expensive? Because dosing is individualized and the drugs are specialized, and the bill is separate from the procedure, making it one of the least predictable costs in the cycle.
Is a guaranteed package worth it? For some families it caps financial risk, but the terms vary and the up-front price is higher, so it should be weighed against your medical profile and tolerance for repeat-cycle cost.
Going into IVF with a line-item understanding of cost turns a vague fear into a plan you can actually fund, and that clarity is especially valuable when IVF is one part of a larger surrogacy budget.